

Loan Calc Hub

- 15.00 Reviews
- 3.5
- Downloads
- 1,000,000+
Our take on Loan Calc Hub from Appgk
When I need a quick answer to “can I afford this repayment?” I usually want a calculator, not a full financial platform. That is the space where Loan Calc Hub makes sense. It is a free finance app from AppDsgnur built around three everyday estimates: loan repayments, fixed deposits, and recurring investments. I found its appeal in the narrow focus. Instead of pushing me through a large money-management system, it gives me a place to test figures before I make a financial decision.
That simplicity is also the first thing to judge carefully. A calculator can help me compare possibilities, but it does not replace the final figures from a bank, lender, or investment provider. My view is that this app is most useful at the early planning stage, when I am changing the amount, rate, term, or contribution and want to understand how the result moves. It is less suitable for someone expecting account management, transaction tracking, personalized advice, or a complete financial dashboard.
How I would decide whether Loan Calc Hub fits
I would start with the question I want answered. If I am comparing a few borrowing options, the loan calculator is the obvious reason to install it. If I am considering a fixed deposit, I can use an estimate to see how the maturity value might compare with leaving money idle. For a recurring investment, the useful question is not simply “what will I have?” but “how does changing my regular contribution or time horizon affect the outcome?” A focused calculator is valuable when I am still exploring those choices.
The app is listed as a finance tool for everyone, and it is free to use. That removes the most common barrier to trying a basic calculator: I do not have to commit money just to examine a scenario. It also makes the app practical for a quick conversation with a partner or family member. We can test a proposed monthly payment, then adjust the figures rather than arguing from a rough guess.
Best Parts of Loan Calc Hub
Things to Keep in Mind About Loan Calc Hub
At the same time, I would not treat a displayed result as a promise. Loan calculations can differ because lenders may use different compounding conventions, fees, insurance charges, taxes, rounding rules, or repayment schedules. Deposit and investment estimates can also depend on the exact product terms and whether returns are compounded or paid in another way. I use Loan Calc Hub as a planning reference, then check the provider’s official illustration before signing anything.
The app has an average rating of 3.5 from around a thousand ratings, while its reach has passed one million installs. Those figures suggest that it has attracted a substantial audience, but they also tell me not to confuse popularity with universal satisfaction. I would judge it by whether its calculations are clear for my own situation and whether I can enter the assumptions without friction.
News and Features Related to Loan Calc Hub

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
Loan planning is where the app has the clearest job
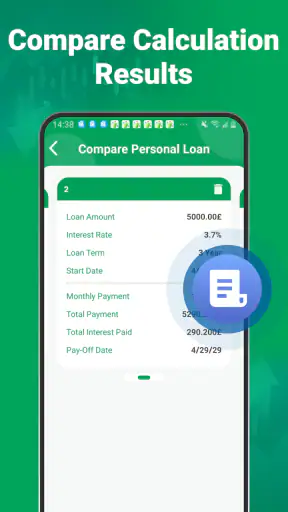
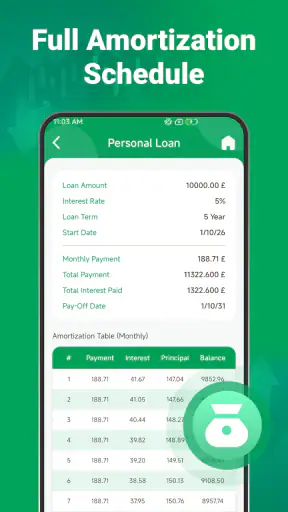
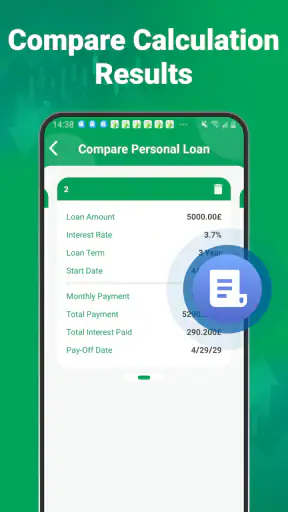
For borrowing, I would use the tool before contacting a lender, not after. Suppose I am considering a loan for a used car. I can begin with the amount I think I need, enter a possible interest rate and term, and look at the estimated repayment. Then I can repeat the exercise with a shorter term. The important insight is often the trade-off: a longer term may make the regular payment look easier, while a shorter term may reduce the total interest. Seeing both versions side by side in my own notes is more useful than focusing only on the smallest monthly figure.
A practical habit is to run a small range of scenarios rather than one “perfect” calculation. I might test the planned amount, a slightly smaller amount, and a slightly larger amount. I would also test two repayment periods. This reveals how sensitive the payment is to the amount borrowed and the length of the agreement. That sensitivity is easy to miss when I look only at the lender’s headline example.
Don't want to read the full review?
Another useful workflow is to calculate the payment before deciding how much cash to keep as a buffer. If the estimated repayment leaves very little room after rent, bills, food, and existing commitments, the problem is not solved by finding a lower advertised rate. I would reduce the borrowing amount or postpone the decision. In that sense, the app is helpful not because it tells me what to borrow, but because it makes an uncomfortable affordability question harder to ignore.
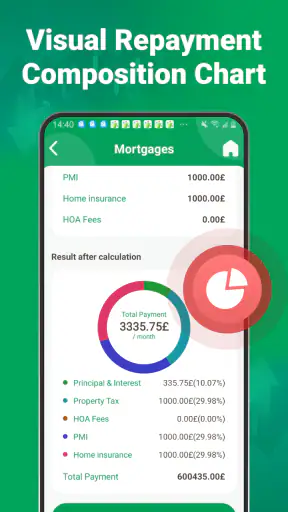
There is a limitation here that matters. A basic loan result may not include every cost attached to a real agreement. I would separately ask the lender about application charges, early repayment conditions, late fees, variable-rate changes, and any required add-ons. I would also confirm whether the rate I am using is the same type shown in the formal offer. Loan Calc Hub can support the comparison, but the final comparison should use the lender’s complete cost, not just the calculator’s repayment estimate.
Screenshots
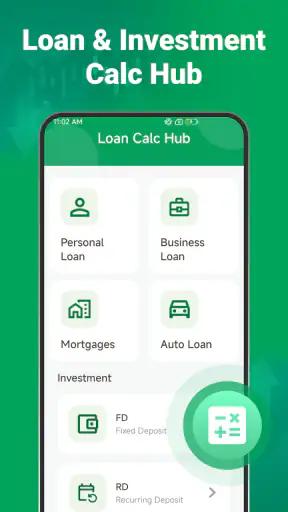
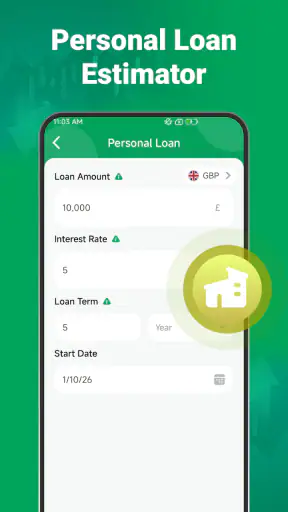
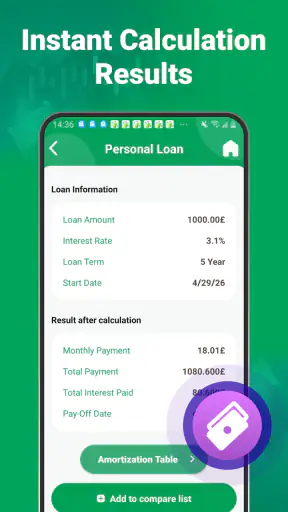
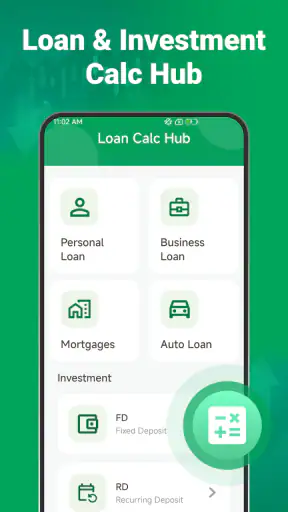
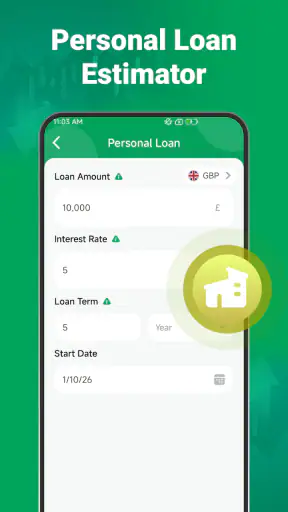
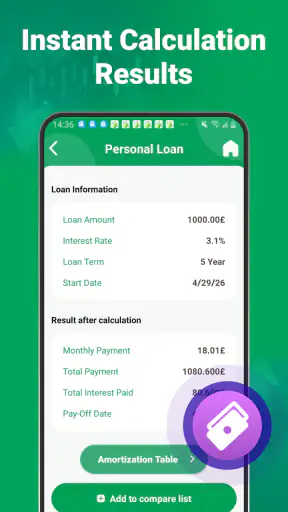
Fixed deposits need more than a maturity number
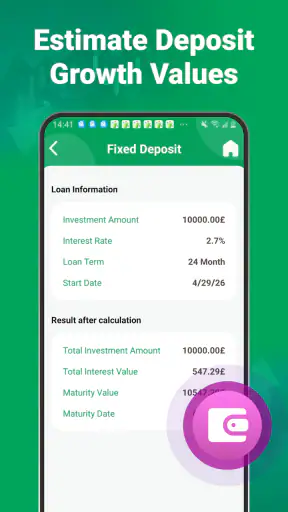
The fixed-deposit calculator is useful for a different kind of decision. Here, I would use it to estimate what a lump sum might become over a chosen period. The result gives me a starting point for comparing the idea of locking money away with keeping it available in a savings account or using it for another goal.
The non-obvious question is liquidity. A fixed deposit can look attractive in a calculation, but I should first separate money I may need soon from money I can genuinely leave untouched. I would run the estimate only on the portion that does not belong in an emergency reserve. If withdrawing early causes a penalty or loss of expected interest under the actual product terms, the calculator cannot make that inconvenience disappear.
I would also use the tool to compare deposit periods, not simply to chase the largest projected maturity value. A longer period may produce a higher result, yet it can prevent me from responding to an unexpected expense or a better opportunity. The right choice depends on when I need the money, not just on the final number shown on screen.
Tax treatment is another reason to treat the output as an estimate. The amount I ultimately keep may differ from the displayed maturity value depending on local rules and the provider’s method of calculating returns. I would use Loan Calc Hub to frame questions for the deposit provider: what rate applies, how often is interest added, what happens at renewal, and what do I receive if I close early?
Recurring investment estimates are best for building discipline
For recurring investments, I would focus less on the final projection and more on the habit represented by the inputs. A regular contribution can turn an abstract goal into a monthly action. I might use the calculator to explore how a modest contribution changes when I extend the time horizon or increase the amount after a pay rise.
One especially useful approach is to test a contribution that I can maintain during an ordinary month, not only during a good month. A projection based on an unrealistic contribution encourages a false sense of progress. I would rather enter an amount that fits my budget, then consider occasional increases separately. This makes the result more useful as a planning tool.
Investment estimates require extra caution because projected returns are not guaranteed. I would not read a calculated future value as a promised outcome, and I would not compare it with a fixed deposit without considering risk, access to the money, fees, and the possibility of losing value. Loan Calc Hub can help me understand the effect of regular contributions, but it does not turn an uncertain investment into a fixed result.
Where it wins, where alternatives fit, and what switching involves
The advantage is a focused starting point
Loan Calc Hub wins when I want three related financial calculators in one lightweight destination. The combination is sensible: borrowing, saving through a fixed deposit, and investing regularly are common parts of household planning. I can move between them while thinking about one goal, such as buying a vehicle, building a deposit, or preparing for a future expense.
It also has a useful psychological advantage over a spreadsheet for quick experiments. A spreadsheet is more flexible, but it asks me to build or find the formulas, label the inputs, and check that I have not made a mistake. A dedicated calculator reduces that setup work. For a person who wants a fast estimate during a conversation, that convenience may be more important than advanced customization.
Compared with a lender’s calculator, the app can be a neutral place to begin. A lender’s tool is naturally tied to that provider’s products and may be excellent for a final quote, but I would not want to start there if I am still deciding how much to borrow. Loan Calc Hub is better suited to the broad first pass, while the lender’s own figures should take over when the product details become specific.
The app’s current version is 1.1.0.0, and it works on devices running Android 9 or later. That makes the compatibility requirement worth checking before installation, especially if I use an older phone. The developer is AppDsgnur, and the app was released on April 24, 2026. I would keep the app updated through the normal store process so that I am using the current version available to my device.
When a spreadsheet or financial platform is better
I would choose a spreadsheet when I need a complete personal model. For example, if I want to combine salary changes, rent, multiple debts, irregular payments, tax assumptions, and savings targets, a spreadsheet gives me more control. I can preserve a history of scenarios and add formulas that match my own situation. The trade-off is that I become responsible for building and checking the model.
I would choose a banking or investment platform when I need live balances, transactions, account access, product-specific rates, or actual contributions. Loan Calc Hub is not the replacement for those services in my decision-making. Its role is earlier and simpler: help me understand a possibility before I enter an account or application flow.
I would also prefer a provider’s official calculator when the exact terms matter. If a lender includes a fee in the financed amount, uses a variable rate, or changes the repayment schedule, a general estimate may not match the formal offer. Likewise, a deposit provider may apply conditions that a general calculation cannot represent. In those cases, using both tools is sensible: Loan Calc Hub for an independent rough comparison, and the provider’s calculator for confirmation.
The real cost of switching from another method
Moving to this app is inexpensive in the obvious sense because it is free, but there is still a practical switching cost: I need to recreate my assumptions. If I already have a spreadsheet with several scenarios, I would not abandon it immediately. I would use Loan Calc Hub to check a few headline cases, then keep the spreadsheet for the detailed record.
If I currently use separate calculators in a browser, the benefit is mainly convenience and consistency. I can keep the same basic questions together instead of searching for a different tool each time. The cost is that I must learn how this app presents its inputs and results. Before relying on it, I would repeat a simple calculation whose answer I already understand and verify that I entered the rate, amount, and period in the intended way.
That verification step is important because calculator errors are often input errors rather than software errors. I would check whether the period means months or years, whether the rate is annual, and whether the contribution is made at the beginning or end of a period when that distinction matters. I would write down the assumptions next to the result. A number without its assumptions is easy to misuse later.
Who should install it and who should skip it
I would recommend trying Loan Calc Hub if you are comparing a few simple financial scenarios and want quick estimates without paying for a planning service. It should suit a first-time borrower checking affordability, a saver comparing deposit periods, or someone testing a realistic recurring contribution. It is also useful for a household discussion because changing one input can make the trade-off easier to explain.
I would skip it as my main tool if I need regulated advice, detailed tax planning, a live view of my accounts, or a formal lender quotation. I would also be cautious if my situation involves several debts, irregular income, complex fees, or investment decisions where risk assessment is central. In those cases, a professional adviser, a detailed spreadsheet, or the relevant provider’s official information may be a better fit.
For a realistic everyday use, imagine that I am planning a home appliance purchase while trying not to damage my monthly budget. I would enter the proposed loan amount, test a shorter and longer term, and compare the estimated payment with the amount I can comfortably spare. Then I would run a recurring-investment scenario using the money I would save by choosing a less expensive model. The app would not make the decision for me, but it would expose the cost of each choice in a way that is easier to discuss than vague intentions.
My recommendation after using it as a decision guide
My recommendation is positive but deliberately limited: use Loan Calc Hub as a first-pass calculator, not as your entire financial planning system. Its free access, focused set of estimates, and broad availability make it easy to test borrowing, fixed-deposit, and recurring-investment ideas. The strongest benefit is speed. I can move from a vague plan to a few concrete scenarios without building a model from scratch.
The best results come from treating every output as an assumption-based estimate. I would save the inputs, test more than one scenario, leave room for ordinary expenses, and verify the final figures with the bank or investment provider. That workflow turns a simple tool into something genuinely useful while avoiding the most dangerous mistake: accepting a neat number as a guarantee.
For me, the decision is straightforward. If I wanted a compact companion for early financial comparisons, I would install it and keep it available. If I needed detailed records, live accounts, or product-specific accuracy, I would use it alongside a spreadsheet or official provider tools rather than instead of them. Its real strength is helping me ask better money questions before I commit.
Loan Calc Hub FAQ
What is Loan Calc Hub used for?
Loan Calc Hub is designed to help users estimate borrowing costs before applying for a loan. After entering details such as the principal amount, interest rate, repayment period, and payment frequency, the app can provide an estimated installment and overall repayment picture. It is useful for comparing scenarios, planning a budget, and understanding how changing loan terms may affect affordability.
Can Loan Calc Hub calculate different types of loans?
The app can generally be used for common installment-based borrowing, including personal loans, vehicle financing, mortgages, and other fixed-payment arrangements. However, the accuracy of the result depends on selecting the correct calculation method and entering the lender’s terms properly. Loans with variable rates, irregular payments, fees, insurance, balloon payments, or unusual schedules may require additional calculations outside the basic estimate.
Are the results from Loan Calc Hub accurate enough for making a financial decision?
Loan Calc Hub should be treated as a planning and estimation tool rather than an official lending calculator. The displayed payment may not include every charge applied by a bank or finance company, such as origination fees, taxes, insurance, penalties, or changes in interest rates. Always compare the app’s estimate with the lender’s official repayment schedule and review the annual percentage rate before signing an agreement.
Does Loan Calc Hub require personal or financial information?
For a basic loan calculation, an app of this type normally only needs figures such as the requested amount, interest rate, loan duration, and payment frequency. You should not need to provide sensitive information such as bank passwords, card numbers, or government identification simply to calculate repayments. Before using the app, review its permissions and privacy policy, particularly if it offers additional features involving saved calculations or financial services.
Is Loan Calc Hub suitable for beginners, and what should I check before downloading it?
Loan Calc Hub can be helpful for beginners because it turns loan figures into easier-to-understand estimates and allows users to test different repayment scenarios. Before downloading, check the app’s latest version, developer information, user reviews, privacy practices, advertising policy, and whether all advertised features are available without payment. Remember that the app does not approve loans or replace professional financial advice.











